Non taxable legal persons in the GCC may need to register

Non taxable legal persons in the GCC may need to register

The three GCC countries which have introduced VAT so far, UAE, KSA and Bahrain, have based themselves on the GCC VAT Treaty to draft their laws. The next country to do so, Oman, has done the same. There is a special group of VAT payers, which fulfill a particular role as stakeholders in the VAT system. They sit on the fringes of the VAT system, not being a full on taxable person, and neither simply a payer, like private persons would be. In the EU, this special group is sometimes called the “group of four”, or the “persons benefiting from a special regime”. These are the non taxable legal persons, the exempt tax payers, the small business and the farmers. Together with the capital assets scheme, it is one of the more technical matters in VAT, and its status under GCC VAT is lacking clarification. Below, we explore the status of the non taxable legal persons. In the upcoming articles, we will be covering the other categories of special taxable persons in the GCC, which are listed below. Going forward we will refer to them as “special tax payers”.
Click here
Stricter UAE Common Reporting Standards require analysis old structures

Stricter UAE Common Reporting Standards require analysis old structures

With increasing globalization and the ease of conducting international financial transactions, the G20 countries requested the OECD to develop a transparent system that would allow jurisdictions to combat off-shore tax evasion and non-compliance effectively. Although exchange of information was not a foreign concept, CRS is one example of an international evolution towards automatic exchange of information (AEOI) based on pre-defined formats. Another such an example is country by country reporting. Drawing inspiration from the Foreign Account Tax Compliance Act (FATCA) in the USA, the OECD Council approved the Common Reporting Standards ("CRS") in 2014, enabling the automatic exchange of financial information between jurisdictions.

Click here
How to file your ESR notification and report

How to file your ESR notification and report

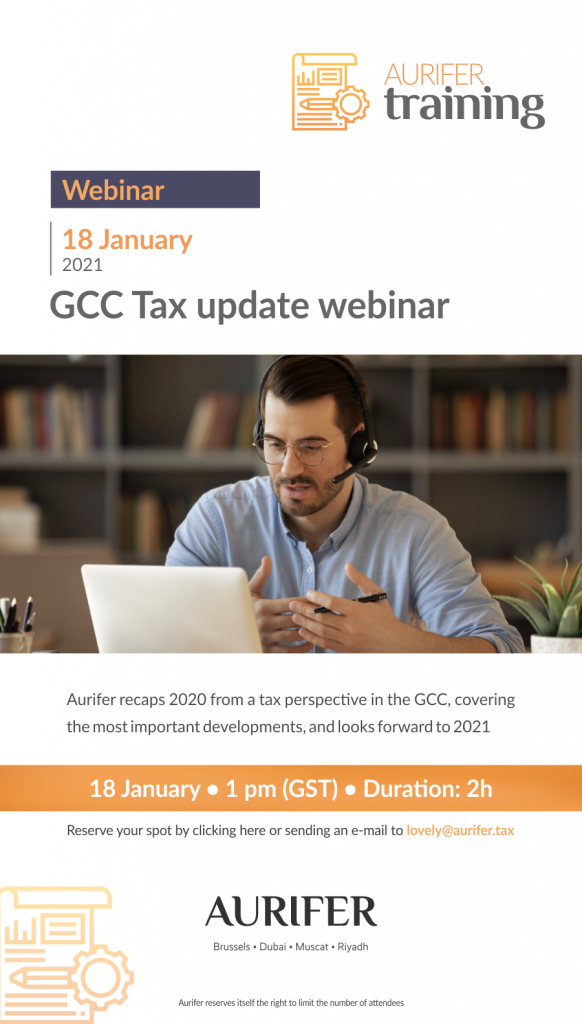
Do not miss our webinar covering the year 2020 in review from a GCC tax perspective. Attend our webinar on 18 January and make sure you are up to date with every single tax development in the GCC. Are you afraid you missed the KSA guides and Circulars? That you missed the Clarifications in the UAE? Did you miss the Omani TP updates? Did you not review the changes in the KSA income tax law? We will cover all important 2020 updates across the GCC and across all taxes. We will also cover our expectations in terms of the 2021 changes. The webinar is a must attend for any in-house tax person. Registration via lovely@aurifer.tax. Seats are limited!

Click here
New UAE disclosure requirements: why consistency is important

New UAE disclosure requirements: why consistency is important

The United Arab Emirates (UAE) is a tax friendly country, imposing no personal income tax and no federal corporate income tax. Nevertheless, it has recently introduced a set of new tax driven disclosure requirements which have significantly increased the level of transparency for individuals and multinational groups with operations in the country.

Click here
E-commerce VAT rules in the GCC: a missed opportunity at perfect harmonization with the EU?

E-commerce VAT rules in the GCC: a missed opportunity at perfect harmonization with the EU?

Few events in the last decade have contributed as much to the growth of the digital economy as Covid-19. The pandemic forced entire populations to go into lockdown, working from home became the norm and outdoor activities were limited to a bare minimum out of fear of infection. All these factors have contributed to a change in consumer behavior as a result of an increase in screen time, which has in turn significantly increased our exposure to digital advertisements. To no one’s surprise, electronic platforms and digital marketplaces have reported an enormous surge in online engagement due to people massively ordering goods and services via the internet. At a time where large numbers of brick-and-mortar stores are experiencing a serious economic slowdown, the e-commerce sector in the GCC is set to reach a value of over $24 billion by the end of 2020, a figure which is $3 billion higher than the projected value of $21 billion (of which more than $2 billion is reportedly due to Covid-19)[1]. It is against the background of a thriving e-commerce sector that we will have a closer look at the applicable VAT rules for electronic services in the GCC [2]. This article does not consider supplies of goods, which are subject to an even more complicated regime in the GCC.

Click here
Working remotely tax free - not that simple

Working remotely tax free - not that simple

The Government of Dubai launched a virtual working program for overseas employees wishing to relocate to Dubai whilst retaining employment in their respective countries. This program aims to enable individuals to utilize the economical and tax advantages associated with residing in Dubai, despite being employed in their countries. While seemingly very attractive, unfortunately it is not that easy for these employees to ensure that their salary will be tax free. In addition, every case may be different. Of course the UAE does not impose Personal Income Tax, but that does not mean that the other jurisdiction will let go that easily.

Click here
Disclosing the UBO in the UAE

Disclosing the UBO in the UAE

Disclosing the UBO in the UAE By way of Cabinet Decision No. 58 of 2020, the UAE has implemented a new UBO regime applicable to businesses established in the UAE, except for ADGM and DIFC businesses. The latter are subject to their own regulations. Government owned businesses are also excluded. Under the new UBO regime, businesses in the UAE are subject to more strict compliance obligations. For some Free Zones, certain requirements were already in place, and therefore the new regime does not change much. The new UBO regime stems from the Anti Money Laundering legislation in the UAE, more in particular Federal Decree-Law No. 20/2018 and its Implementing Regulation. It is suspected to targets amongst others disclosures of nominee structures. The new UBO regime requires businesses in the UAE to maintain beneficial ownership and shareholder registers at their registered office, and to submit information from these registers to their regulatory authority (e.g. DED or Free Zone Authority). Any changes in the information previously provided, need to be disclosed as well.

Click here
Register now for our webinar on the brand new Omani VAT Law

Register now for our webinar on the brand new Omani VAT Law

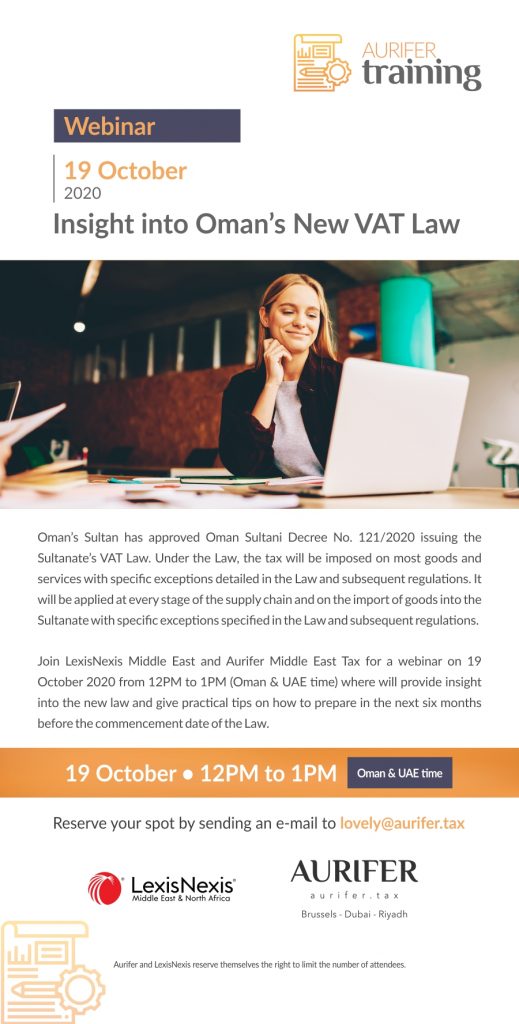
On 12 October 2020, His Majesty Sultan Haitham bin Tarik issued Royal Decree 121/2020 to implement Value-Added Tax (VAT) in Oman. The Decree is expected to be published on the next official Gazette on 18 October 2020. Watch this space for the English translation. The law will come into force 6 months after the publication, in April 2021. The standard VAT rate will be 5% and will be levied on most goods and services, with exceptions made to some supplies, which will be zero-rated or exempt. The Omani law is a closer sister to the UAE VAT law and will follow the Bahraini law, applying hefty penalties, including, in some cases, imprisonment (i.e., failure to register for tax). VAT is being implemented in response to severe financial and economic repercussions COVID-19 outbreak - amplified pre-existing fiscal strains and low oil prices. The IMF estimated generation of new revenue between 1.5 and 3 percent of non-oil GDP, from the introduction of VAT. Taxpayers will have a little over six months of preparation time before the commencement date of the law. The Executive Regulations will be published in December. Registration are expected to open in January 2021. Register for our webinar via lovely@aurifer.tax

Click here